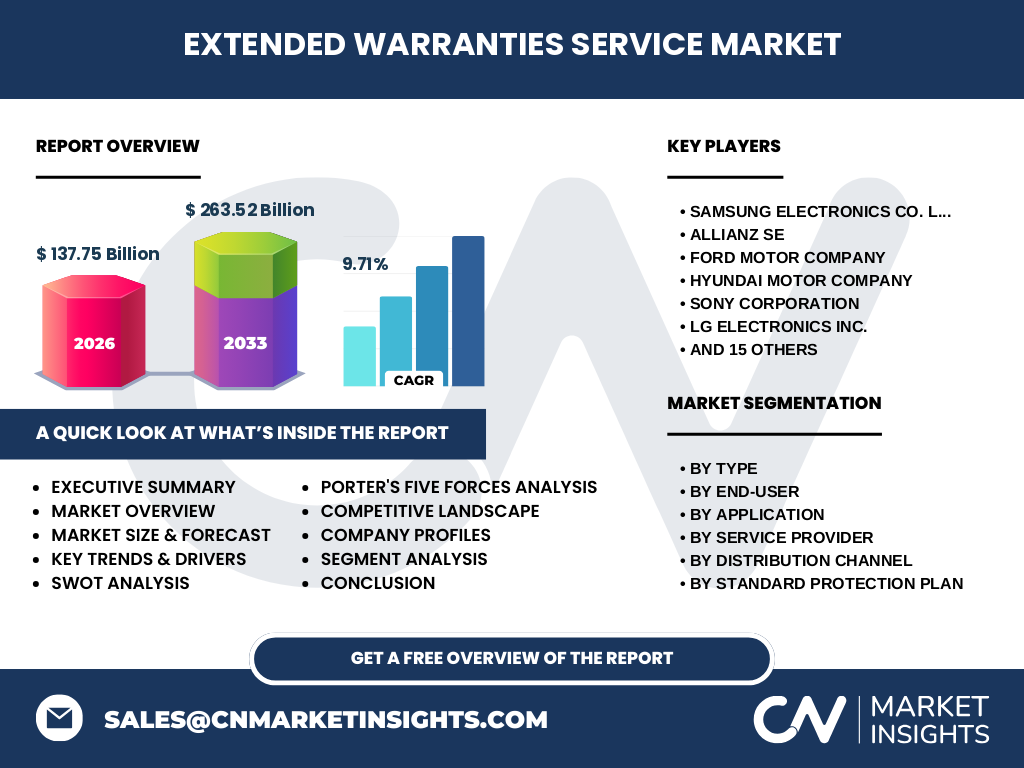
Market Overview: Defining the Extended Warranties Service Market
The Extended Warranties Service Market represents a critical financial safeguard for asset longevity. Currently valued at 137.75 Billion in 2026, this sector encompasses service contracts providing post-warranty coverage for automobiles, mobile devices, and home appliances. By mitigating repair costs, it provides essential risk transfer mechanisms for both individual consumers and corporate entities, ensuring operational continuity in an era of complex, high-value consumer electronics.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by the increasing complexity of electronic components, which makes DIY repairs impossible. Key drivers include rising consumer reliance on mobile devices and automobiles. However, market restraints persist, such as regulatory scrutiny regarding hidden clauses and logistical hurdles in global supply chains. Opportunities lie in integrating AI-driven diagnostics to streamline claim processing and enhance customer satisfaction.
Emerging Trends and Strategic Growth Patterns
A pivot toward digital-first experiences is reshaping the industry. We see companies like Get Mulberry transforming the user experience through embedded, transparent coverage options. Another trend involves the rise of proactive maintenance coverage over reactive repair models, leveraging IoT data from appliances to anticipate failure before it disrupts the end-user, significantly increasing the value proposition of standard protection plans.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic acted as a dual-edged catalyst; while supply chain disruptions initially slowed hardware sales, they simultaneously heightened consumer sensitivity toward financial protection. Our research shows that the subsequent recovery trajectory accelerated the adoption of online distribution channels. As repair services faced labor shortages, the market shifted toward remote diagnostic solutions, permanently altering the way service providers interact with the global consumer base.
Competitive Benchmarking and Market Concentration
The market remains moderately concentrated, characterized by a mix of traditional insurers like Allianz SE and The Allstate Corporation alongside specialized warranty administrators such as Asurion LLC and Assurant Inc. Strategic dynamics are shifting as tech-native players challenge incumbents by prioritizing seamless integration into retail point-of-sale systems, forcing legacy manufacturers like Sony Corporation to rethink their captive service offerings.
Executive Summary: High-Level Market Synthesis
The Extended Warranties Service Market is poised for significant expansion, with a forecasted valuation of 263.52 Billion by 2033. Driven by a robust CAGR of 9.71%, the sector is moving toward extreme personalization. This synthesis indicates that stakeholders must pivot toward hybrid protection plans—blending accidental coverage with comprehensive repair services—to maintain a competitive edge in a saturated global electronics and automotive landscape.
Market Forecast: Growth Trajectory from 2027 to 2033
Our projections indicate that the market will maintain a steady 9.71% CAGR through the 2027-2033 period, reaching a total valuation of 263.52 Billion. This trajectory reflects increasing penetration in emerging economies and the integration of extended warranty services into the subscription-based economies. Analysts expect the most aggressive growth within the Mobile Devices and Automobiles segments as repair costs continue to climb globally.
Segmentation Analysis: Categorization and Market Utility
Segmentation provides the granular clarity necessary for strategic planning. We categorize the market by Type (Standard vs. Accidental), Application (Automobiles, Home Appliances, Mobile Devices), and Provider (Manufacturers, Retailers, Third-Party). This breakdown reveals that Accidental Protection Plans are becoming the growth engine, driven by the inherent fragility of modern mobile hardware compared to traditional home appliance coverage models.
Regional Market Performance and Geographic Distribution
Regional dominance is currently held by North America and Europe, where consumer awareness of risk mitigation is highest. However, the Asia-Pacific region is emerging as the fastest-growing frontier. Regional performance is heavily dictated by local consumer protection laws and the prevalence of organized retail infrastructure, which facilitates the distribution of high-margin third-party service contracts compared to fragmented emerging markets.
In-Depth Regional Review: Key Geographical Dynamics
In North America, Best Buy Co. Inc. leads via mature offline channels, while in Asia-Pacific, OneAssist Consumer Solutions Pvt. Ltd. is capitalizing on the massive shift toward smartphones. European markets face unique regulatory constraints regarding insurance product transparency, requiring providers to maintain stringent compliance standards. Our analysis suggests that localized service delivery remains the single biggest differentiator for success in fragmented regional markets.
Company Profiles: Strategic Positioning of Leaders
Major players display distinct strategic focuses: Ford Motor Company and Nissan North America Inc. leverage captive financing to bundle warranties with vehicle sales, while AmTrust Financial Services Inc. and CARCHEX LLC dominate through specialized vehicle protection. Meanwhile, tech-focused entrants like Get Mulberry and Consumer Priority Service Inc. prioritize digital agility, targeting Gen Z and Millennial consumers with mobile-optimized service interfaces that drive higher conversion.
Porter's Five Forces: Competitive Intensity Assessment
The Extended Warranties Service Market exhibits high competitive intensity. Buyer power is moderate, but supplier power (in the form of authorized repair parts) is high, giving manufacturers an advantage. The threat of substitutes is low due to the increasing cost of proprietary electronics repairs, while the threat of new entrants is mitigated by the regulatory capital requirements inherent in the insurance-based components of these services.
SWOT Analysis: Strategic Health Assessment
Strengths: High brand loyalty and recurring revenue models. Weaknesses: High customer acquisition costs and complex claims administration. Opportunities: Expanding into the Smart Home and Electric Vehicle segments to capture new lifecycle value. Threats: Increasing regulatory scrutiny from bodies like the FTC and potential shifts toward universal Right-to-Repair legislation, which could erode the necessity of traditional manufacturer-backed extended warranties over time.
Value Chain Analysis: From Raw Materials to End-Users
The value chain initiates with the original equipment manufacturer (OEM), flowing through risk underwriters like Allianz SE, and ultimately reaching the end-user via retail point-of-sale or digital platforms. The true value flow is increasingly captured by Third-Party Providers who aggregate risk across multiple brands, providing a more cost-effective repair network than original manufacturer service centers, which often operate with high overheads and restricted parts access.
Investment Insights: Strategic Recommendations
Investors should target companies that possess vertically integrated diagnostic capabilities. High-potential areas include the Automotive EV battery protection segment and B2B enterprise appliance coverage. We recommend prioritizing service providers who demonstrate high digital maturity, as the integration of telematics and AI into service contracts is clearly the most scalable path to increasing margins in the 2027-2033 cycle.
Conclusion: Key Takeaways for Stakeholders
The Extended Warranties Service Market is a high-growth environment characterized by a transition from basic mechanical coverage to data-driven risk management. With the market projected to reach 263.52 Billion, success depends on the ability to integrate seamlessly with digital commerce and provide transparent, accessible claims resolution. Stakeholders should focus on the mobile and automotive segments, where the demand for protection remains essentially inelastic.
Research Methodology: Triangulating Market Data
Our baseline estimates are derived from a triangulation methodology. We cross-reference trade registry data and annual reports from listed companies like Samsung Electronics Co. Ltd. and LG Electronics Inc. with primary interviews from insurance underwriters and retail channel managers. These data points are adjusted against macroeconomic indicators and local regulatory shifts to ensure the 9.71% CAGR estimate reflects both realized and latent market demand.
Scope of the Report: Coverage Parameters
This report covers the global Extended Warranties Service Market, focusing on consumer electronics, automobiles, and home appliances. The scope includes geographic assessment of North America, Europe, and Asia-Pacific, evaluating both B2C and B2B segments. Limitations include the exclusion of warranty extensions provided directly through credit card perks, focusing instead on dedicated, stand-alone service contracts purchased at the point of sale or post-purchase.
Recent Developments: Strategic Market Moves
Recent developments highlight aggressive partnerships between retailers and specialized warranty administrators. Best Buy Co. Inc. has expanded its service offerings to include more comprehensive Accidental Protection Plans, reflecting a market-wide shift toward covering user-error. Furthermore, Haier Group and Delta Electronics Inc. have increasingly integrated API-driven warranty activation into their global product launches, streamlining the consumer enrollment process and reducing the friction between product purchase and service coverage.